All Categories
Featured

Readying for 2026 Medicare Advantage Enrollment
Table of Contents
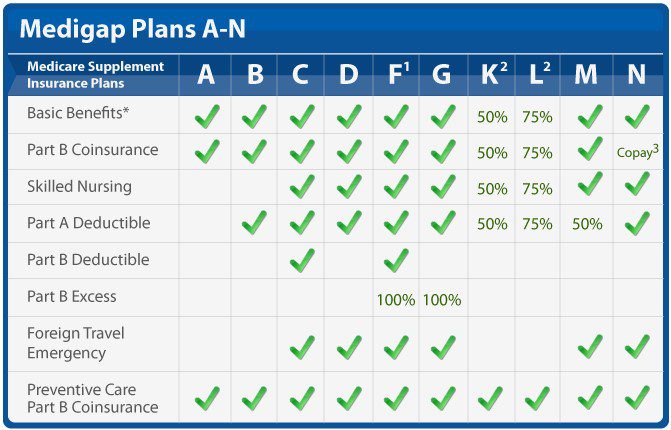
Medicare Supplement prepares expense $180 per month, on average, in 2026. These plans have the best protection for elders new to Medicare. A Medigap Plan G policy covers nearly all the costs you're usually responsible for with Medicare, other than for the $283 annually Part B deductible. Medigap Plan F normally does not make good sense economically.
Insurance in Yorba Linda CAA high-deductible Strategy G expenses just $52 per month, typically. However, that doesn't always make it a bargain. That's since you have to pay $2,950 for medical care each year before coverage starts for either strategy. You're better off with a routine Plan G Medigap policy if you expect to consistently need a lot of medical care.
F$ 227G$180N$137C$243B$205D$198A$168M$154L$134K$87High-deductible F$ 58High-deductible G$ 52Show All Rows Just how much you pay is based on several elements, including: The strategy you select The business you select Where you live Your age and gender (usually) Discounts you qualify for When you registered Massachusetts, Minnesota and Wisconsin have various Medicare Supplement plans than the rest of the nation.
In Massachusetts, you can choose between 3 various types of Medigap strategies: Core, Supplement 1 and Supplement 1A. In Minnesota, the finest Medicare Supplement choice for many people is the Basic strategy. This plan offers a comparable level of coverage as Medigap Plan G. The Basic strategy covers almost all the costs you are accountable for with Original Medicare (Components A and B).
Evaluating Your Benefits of Indexed Universal Life Plans
The Extended Basic strategy uses a lot more coverage. It pays for your Medicare Part A deductible, foreign travel emergencies, preventive services not covered by Medicare and additional expenses you are accountable for if your medical professional doesn't accept the cost set by Medicare. However, this plan is generally not a great choice due to the fact that of its high cost.
In other words, you can build your own Medigap strategy by including coverage bonus to your policy. Base plans require to cover specific advantages like your Part A (healthcare facility care) coinsurance or copay, 175 days of psychological health inpatient care and some of the costs you're responsible for paying with Part B (doctor sees).

Numerous business let you customize your policy with protection additionals, generally at a higher expense. You can choose a Base strategy choice with a lower monthly rate, but you'll pay more when you visit the physician. High-deductible strategies: You'll pay more before protection starts. 25% cost-sharing strategies: You'll pay approximately 25% of your medical costs, similar to Strategy L.
Selecting Your Best 2026 Medicare Supplement Plans
Select a Medigap policy by comparing strategy benefits and costs versus the medical care you anticipate to require. Attempt to match your protection with your specific medical needs. It may not make sense to get a policy with excellent coverage like Strategy G or F if you're in good health and you don't go to the doctor frequently.
If you have a disability or ongoing illness, or you just desire the peace of mind of having excellent protection as you get older, you should choose a strategy with much better protection like G, F or N. Even though these strategies have higher average rates, you'll conserve cash when you go to the healthcare facility.
If you desire the versatility to quickly change from an inexpensive strategy to a plan with much better coverage, Blue Cross Blue Guard is the best alternative. Its Blue to Blue rule means you can switch Medigap strategies at any time without paying a greater rate due to the fact that of your age or health status.
In specific, take a look at cost and customer care. Keep in mind, strategies have the very same coverage if they have the very same letter. A Plan G will have the same protection regardless of whether you purchase it from AARP/UnitedHealthcare or Blue Cross Blue Guard. While the protection is the exact same, plan costs can differ by hundreds of dollars a year.

Securing Final Expense Insurance for Seniors and Families
You don't desire to select a company that has poor client service, because that can cause issues down the road. Before you pick a Medicare Supplement business, check to see if you can get discount rates. For instance, family discounts for couples, civil partners and extended relative who live together are a typical method to save.
Depending upon where you live, you might likewise have the alternative to choose a low-cost Medicare Select strategy. These policies have the same coverage as a routine Medigap plan, but they limit you to a network of doctors like an HMO. You no longer need a broker to purchase a Medigap policy.
Remember that your Medigap expenses depend in part on where you live, and strategy schedule varies by county. You can also buy a Medicare Supplement plan straight from a business's website.

Latest Posts
Securing Burial Insurance for Seniors
How IUL Benefits Secure Retirement
Reviewing Term and Whole Plans